


Carbon capture, utilisation and storage (CCUS) adoption remains uneven across industries, but investment is expanding into hard-to-abate sectors and power generation, according to GlobalData.
The intelligence firm’s Strategic Intelligence report,
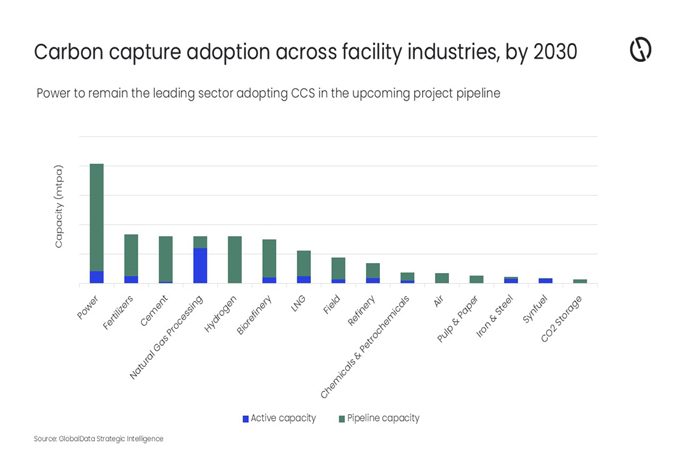
“Carbon Capture and Storage,” finds that natural gas processing currently
accounts for the largest share of active CCUS capacity because of its
concentrated CO₂ streams and established commercial applications.
However, the project pipeline is increasingly focused on
power generation and other emissions-intensive industries.
Ravindra Puranik, Oil and Gas Analyst at GlobalData, said:
“CCUS technologies are designed to capture CO₂ from point sources, such as flue
gas emissions, to prevent it from being released into the atmosphere. In the
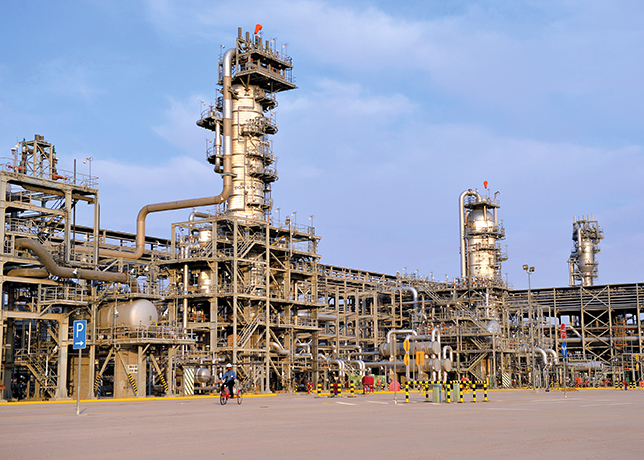
oil and gas industry, CCUS is primarily used to remove CO₂ from natural gas at
gas processing plants and LNG liquefaction terminals. Notably, the Terrel/Val
Verde gas processing plants in the US were among the first to implement it at a
commercial scale.”
Power generation is expected to become the leading sector
for upcoming CCUS capacity, with 73 million tonnes per annum (mtpa) in projects
forecast to come online by 2030.
GlobalData said the growth reflects rising electricity
demand, continued reliance on dispatchable thermal generation and efforts to
extend the operating life of existing assets while reducing emissions.
CCUS is also gaining attention in hydrogen production,
particularly across refineries, petrochemical plants and fertiliser facilities.
Most captured CO₂ is currently used for enhanced oil
recovery, but permanent storage in deep geological formations represents a
longer-term opportunity.
Occidental Petroleum, ExxonMobil, Equinor and Eni are among
companies developing storage sites. Captured CO₂ can also be used in synthetic
fuels, beverage carbonation, concrete curing and controlled-environment
agriculture.
Puranik said: “The next phase of CCUS deployment is therefore likely to be shaped by two parallel drivers: near-term decarbonisation of large industrial emitters and longer-term demand for carbon removals. This is expanding adoption beyond natural gas processing into power, hydrogen, refining, cement, bioenergy, and direct air capture (DAC), although project execution remains dependent on policy support, storage access, and commercial viability.” -OGN/TradeArabia News Service