


As AI data centres and high-density digital loads stretch power grids to their absolute physical limits, the global energy transition is quietly triggering a revolution in power electronics and thermal management.
At the centre of this shift is synthetic diamond, an ultra-wide bandgap material capable of displacing traditional copper spreaders and silicon carbide (SiC) semiconductors to deliver unprecedented energy efficiency and heat dissipation.
Yet, as sovereign wealth funds across the GCC, US, and Asia pour billions into energy infrastructure, public equity markets have spun ahead of commercial reality, driving speculative surges on headline promises rather than active revenues.
In this exclusive interview with OGN energy magazine, Nagham Hassan, Market Analyst at etoro, unpacks the intersection of energy density, geopolitical supply chains, and market fundamentals; and analyses whether diamond thermal technology is ready to power the next generation of energy infrastructure, or if deployment timelines remain years behind market hype.
Below are excerpts from the interview:
As public utilities and independent power producers face soaring infrastructure costs to support high-density digital loads, could diamond-enabled energy efficiency improvements materially impact long-term corporate credit ratings in the power sector?
Honestly, it is too early for anyone to answer this credibly. Diamond cooling only reached the market recently, and the companies selling it say the revenue barely shows in their accounts.
The technology also has not passed its main commercial test yet, getting costs close enough to copper for buyers to switch at scale.
The efficiency case is real and proven in the lab, which is why money keeps flowing into the sector.
But a credit rating effect would come several steps after mass adoption, and mass adoption has not started.
The 2027 and 2028 production milestones will tell us more.
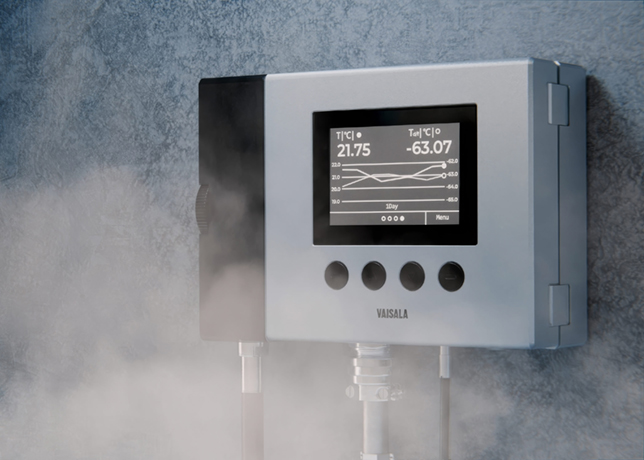
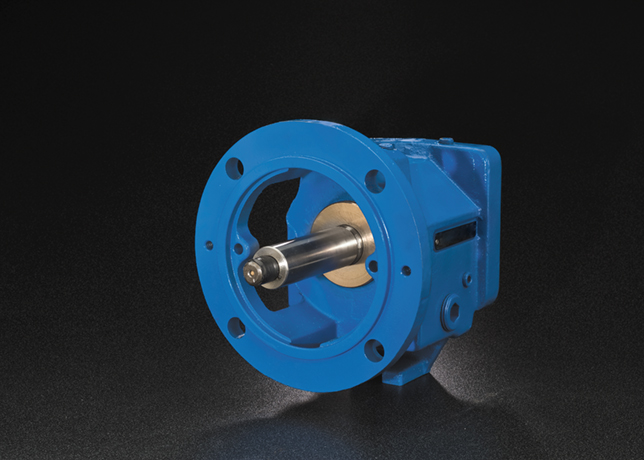
Synthetic diamond cooling technology offers unprecedented thermal management solutions
How do you anticipate institutional asset managers will reallocate capital between established wide-bandgap incumbents like Silicon Carbide (SiC) producers and emerging synthetic diamond pure-plays over a five-year investment horizon?
The first thing to know is that real synthetic diamond pure-plays are hard to find on public markets.
The technology leaders are private, so what trades today is the supply chain around them, material producers, toolmakers and equipment firms, mostly in China and Japan.
The silicon carbide side carries its own lesson.
Wolfspeed, the main SiC pure-play, went bankrupt last year because it built factories faster than revenue arrived, and the market learned that a material could succeed while its purest stock fails.
So over five years, I expect capital to move toward diversified companies working with both materials, some SiC producers are already developing diamond composites, rather than a clean switch between the two.
Considering the massive sovereign investments in AI data centres and renewable energy across the GCC, how attractive is the region’s capital market ecosystem for funding next-generation semiconductor infrastructure and supply chains?
The Gulf is attractive for this industry, but not mainly through its stock markets.
Government wealth funds pay for the buildout directly, and the stock market comes at the end, when mature companies get listed, the way Presight and Space42 now trade in Abu Dhabi.
This order suits chip making well, because chip plants lose money for years before they earn, and government funds can wait that long.
The model is no longer purely sovereign either. Microsoft put $1.5 billion into G42, and Stargate UAE brings OpenAI, Oracle, Nvidia and SoftBank into one Abu Dhabi project.
Diamond has no documented Gulf fund investment yet, but DMCC’s new industrial diamond hub fits the region’s pattern: Infrastructure first and investment once the technology proves itself.
Upstream synthetic diamond synthesis faces potential market supply saturation
Diamond is often discussed as one investment story. Should investors treat diamond cooling and diamond chips as the same opportunity?
No, and mixing them up caused much of this year’s mispricing.
Diamond cooling exists today: Heat spreaders are shipping in small volumes; the first orders have landed, and the business case is about beating copper on cost.
Diamond chips are a different product on a different timeline.
The technology is proven in the lab, and the first mass production plant in Japan targets full output in fiscal 2028, competing against silicon carbide rather than copper.
As state-backed manufacturing initiatives emerge in Japan, the UK and the US, how will government subsidies and sovereign industrial policy alter private venture capital and equity risk profiles in the sector?
Government money is already deep in this sector.
For instance, Ookuma holds multi-year commissioned research from Japan’s Defence Ministry, Diamond Foundry’s Spanish plant carries 81 million euros of Spanish state aid, and Japan’s policy bank is financing the Georgia plant in the US.
A company with that kind of backing rarely goes under.
The bigger danger for venture investors is betting on a company that governments pass over, because in this sector it is governments that pick the winners.
And since these leaders are all private, venture rounds are the only way to invest in them at all.
Listed stocks feel those same decisions in real time.
When Washington announced its Georgia diamond plant with De Beers unit Element Six as manufacturer, Japan’s EDP, whose shares had been rising on hopes that a Japanese producer would be chosen, lost a fifth of its value in two days.
Following China’s export restrictions on super-hard materials, how are Western retail and institutional investors pricing supply chain concentration risk into upstream material suppliers versus downstream chip packaging firms?
The honest answer is that this pricing cannot really be observed, because the Western side of this industry is almost entirely private.
Leaders like Diamond Foundry and Akash Systems have no listed shares, and the main listed player, Coherent, grows its own diamond, so China supply risk barely applies to it.
There is simply no clean way to read a risk premium from Western share prices.
The money building a Western supply chain is coming from governments, with the US and Japan financing diamond production on American soil to cut dependence on China.
As for the restrictions themselves, they were suspended before ever taking effect and stay on hold until November 10, 2026, so no supply has actually been cut so far.
Given that fully diamond-based power chips remain years away from mass commercialisation, where in the value chain, from lab-grown diamond synthesis to thermal spreader packaging, do you see the most defensive risk-adjusted returns today?
Each stage of this supply chain carries a different risk profile.
In the upstream, where the companies are growing the diamond themselves, there is synthesis. It looks like the heart of the sector, but it carries the most risk.
China already makes about 95 per cent of the world’s synthetic diamond. And now countries are building their own production to reduce reliance on China, and today’s high margins are drawing in even more suppliers.
Although that points toward saturation, however, the midstream is more resilient and is the most defensive part of the chain.
Here, equipment suppliers gain fresh demand for cutting and polishing machines, and diamond toolmakers gain the chip sector as a new customer, so established revenue carries both if adoption runs late.
Meanwhile, downstream, thermal spreader packaging sits closest to real demand and holds the first orders, but most of it belongs to private companies, out of reach of public markets.
Given your observation that market valuations are outpacing present-day earnings, how should energy sector investors differentiate between speculative momentum and fundamentally sound asset pricing in listed diamond semiconductor stocks?
Several Chinese companies have stated that lab-grown diamond cooling technology is still in its infancy and contributes nearly nothing to their core businesses.
The market values the sector on future possibilities, like diamond chip cooling and ultra-high-efficiency diamond power semiconductors, while most of these companies still earn their revenue from traditional businesses such as abrasives, cutting tools and gem-grade stones.
This mismatch between today’s earnings and tomorrow’s story fuelled a massive wave of speculative hype in early 2026.
So before buying any of these stocks, ask three questions: Does the company report real diamond cooling or wafer revenue in its results, or just talk about diamond in its press releases? Has something concrete actually happened, a product delivered, a factory running, a contract signed? And does the company have a strong existing business that generates enough revenue to carry it until diamond products become a real market?
With an index of listed Chinese diamond companies having more than doubled following export restrictions on super-hard materials, how much downside risk exists for equity portfolios if commercial deployment timelines slip beyond 2028?
A correction first: The sector more than doubled on reports that Nvidia would use diamond to cool its next AI chip, not on China’s material ban.
The ban was announced in October 2025 but never actually enforced.
China suspended the rules until November 10, 2026, and the industry should mark that date on its calendar.
So far, this market has only moved on headlines, but if China enforces the ban, it will face a real supply restriction for the first time.
When it comes to equity portfolios, the distinction that matters is ownership. Most of the sector’s major players are privately held, including Akash Systems, Ookuma Diamond Device, Diamfab, Diamond Foundry and others, and those are the companies signing the deals and seeing the early revenue.
The broader listed names are rallying on news about these private companies, not because of their own business.
That distinction is critical, because a delay beyond 2028 would hit the listed stocks hardest.
Their prices rest on a story unfolding at other companies, with no earnings of their own to support a floor.
The private players, meanwhile, could absorb a delay far more quietly.
What specific financial metrics, such as capital expenditure efficiency, order backlog growth, or gross margin expansion, should financial analysts monitor to verify that diamond thermal management is translating into repeatable revenue?
The suggested metrics assume a maturing business, but this sector is still in its early stages, so the numbers that matter now are more basic.
Everything begins with cost, because cost decides whether adoption happens at all.
Diamond cooling parts reportedly sell for three to four times the price of copper ones, and the industry believes buyers will switch once that gap narrows to about twice the cost of copper.
Companies pushing costs toward that level are building a genuine lead.
Adoption then has to show up as orders, especially repeat orders, meaning the same customers coming back.
High margins can also be misleading in this sector.
Diamond heat spreaders earn strong margins today only because few producers can make them.
This industry has crushed its own prices before. For example, when lab-grown gem diamonds became profitable, so many factories entered causing prices to fall from about $100 a carat to 15 within two years.
The durable signal is margins that hold as supply grows.