


Global investment in uranium exploration and mine development is increasing as countries prepare for a potential expansion of nuclear energy, but significant investment will be needed to ensure future supply, according to a new report by the OECD Nuclear Energy Agency (NEA) and the International Atomic Energy Agency (IAEA).
The Uranium 2026: Resources, Production and Demand report,
known as the “Red Book”, examines uranium resources, production, exploration
and reactor requirements, drawing on data from 46 countries.
It covers 2023 and 2024, with selected information from 2025
and 2026.
As of January 1, 2025, 418 commercial nuclear reactors were
operating worldwide, with combined net capacity of 378 GWe and annual uranium
requirements of around 64,500 tonnes of uranium (tU).
Another 23 reactors, with total capacity of 19.7 GWe, were
in suspended operation.
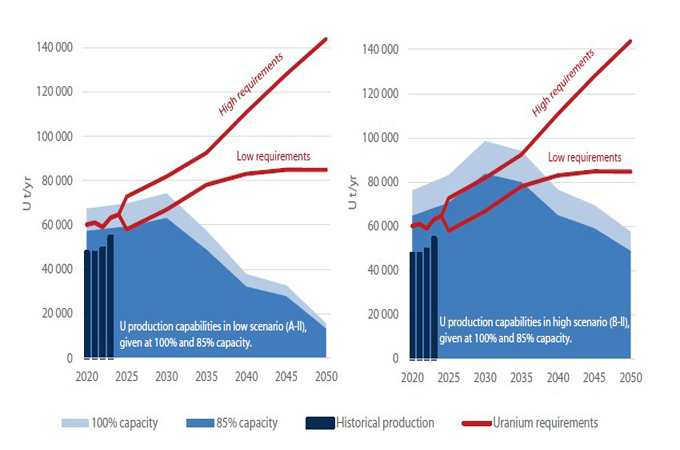
The report projects global nuclear generating capacity to
increase substantially by 2050 as countries seek to meet rising electricity
demand, strengthen energy security and advance environmental goals.
Depending on the growth scenario, annual uranium
requirements could reach between approximately 84,800 tU and 143,900 tU by
2050.
The report estimates that identified uranium resources
recoverable at costs below $260 per kilogramme of uranium exceed 8.1 million
tU, up 2.1 per cent from the previous edition.
This resource base is
sufficient to meet even the highest projected demand through 2050.
However, the NEA and IAEA warned that resource availability
alone does not guarantee supply security.
Uranium mining projects typically require 15 to 20 years to
develop, making early exploration, permitting and investment essential to
prevent future shortages.
The report said sustained uranium prices and long-term
contracts will be important to maintain exploration activity, support
investment decisions for new mines and encourage innovation in extraction and
processing technologies.
Uranium production has also strengthened.
Global output increased by around 20 per cent in 2023 and
2024 compared with the previous two years, exceeding 116,000 tU. Production
reached 61,924 tU in 2024, the highest level since 2016.
The increase was driven mainly by the restart of previously
idled capacity and higher production from existing mines, particularly in
Canada.
While several projects received regulatory approvals and
moved toward development, no new uranium mining projects entered production.
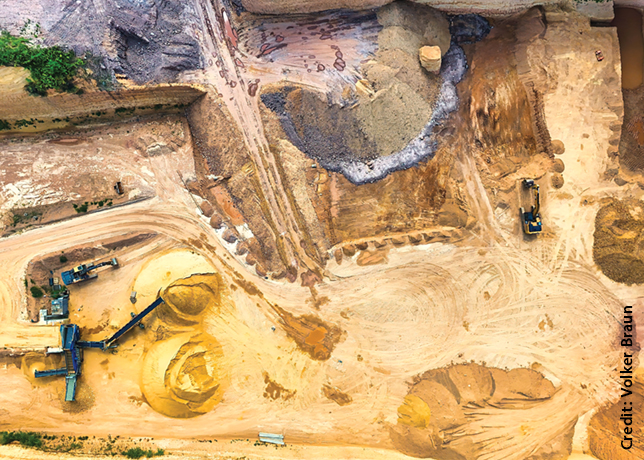
Global exploration and development spending exceeded $1.78
billion in 2023–2024, up around 46 per cent from 2021–2022.
Although exploration drilling increased significantly,
drilling focused specifically on project development remained largely stagnant,
highlighting the need to strengthen the pipeline of new uranium mines.
The report concludes that continued investment across the uranium supply chain will be critical as nuclear power expands and demand for uranium rises over the coming decades. -OGN/TradeArabia News Service